Tag: personal-finance

  • Retirement 101: Learning How to Be Retired

    Retirement 101: Learning How to Be Retired

    Click below the title and paste this article body:

    Most retirement advice concentrates on reaching retirement. We are told how much to save, when to claim Social Security, how to choose investments, and how to leave the workforce. Far less attention is given to what happens after we succeed.

    Retirement is not simply the absence of a job. It is a new stage of life with unfamiliar freedoms, responsibilities, and choices. Learning how to use that freedom well is a skill—and like any skill, it improves through attention, practice, and adjustment.

    The Structure We Leave Behind

    A full-time career provides more than income. It also gives us a schedule, responsibilities, goals, social contact, feedback, and a reason to get moving in the morning.

    When work ends, those structures can disappear at the same time. The first weeks may feel like a long-awaited vacation, but a permanent vacation is not the same thing as a satisfying life. Eventually, we must decide how our days will work when no employer is organizing them for us.

    Some retirees naturally create new routines. Others drift, become isolated, or wonder why retirement does not feel as rewarding as expected. The difference is not necessarily money. It is often structure.

    Replacing a Job Is Not the Goal

    A successful retirement does not require filling every hour or recreating the pressure of employment. The goal is to build enough structure to support the life we want.

    That might include regular exercise, household projects, volunteer work, travel, creative pursuits, caregiving, learning, or time with friends and family. The right combination will differ for every person.

    The important point is that a satisfying week rarely appears by accident. We create it by deciding which activities deserve a regular place in our lives.

    Purpose Can Be Smaller Than a Career

    Many people associate purpose with major accomplishments, leadership positions, or paid work. That can make retirement feel like a loss of importance.

    But purpose does not need to be grand. It can come from helping a neighbor, caring for family, maintaining a home, learning a skill, improving our health, preserving family history, or contributing to a community.

    A career may give us one large source of purpose. Retirement allows us to build several smaller ones. Together, they can be more personal and more durable than a job title.

    Identity Also Changes

    For decades, one of the first questions we hear when meeting someone is, “What do you do?”

    Our answer often becomes part of how we understand ourselves. When the job ends, the title remains in the past tense. That transition can be more difficult than expected, especially for people whose careers carried responsibility, status, or a strong sense of mission.

    We do not have to discard that history. Our experience remains part of us, but it no longer has to define all of us. Retirement creates room to recover interests that were postponed, develop new abilities, and decide who we want to be without an organizational title.

    Relationships Need Attention

    Work provides routine contact with other people, even when those relationships are not especially close. Retirement can sharply reduce that contact.

    At the same time, spouses or partners may suddenly spend far more time together than before. Both changes require adjustment. Healthy retirement relationships benefit from a balance of shared activities, individual interests, friendships, and time alone.

    Social connection should be treated as part of retirement planning, not as an optional extra. Isolation can develop gradually, so it is easier to maintain connections than to rebuild them after they disappear.

    Retirement Is an Ongoing Experiment

    We do not need to design the perfect retirement on the first day. In fact, we probably cannot.

    A better approach is to treat retirement as an ongoing experiment. We try routines, activities, trips, volunteer roles, and hobbies. We pay attention to what gives us energy and what feels like an obligation. Then we adjust.

    Some plans will work. Others will not. Changing direction is not failure; it is part of learning how this stage of life works for us.

    The First Retirement Skill

    The first skill of retirement is recognizing that retirement itself deserves to be learned.

    Financial security creates options, but it does not automatically create purpose, structure, health, or connection. Those parts of retirement require their own planning and practice.

    We spent years learning how to work. We can give ourselves permission to spend time learning how to be retired.
  • Pretirement: Test-Drive Your Retirement Before You Retire

    Pretirement: Test-Drive Your Retirement Before You Retire

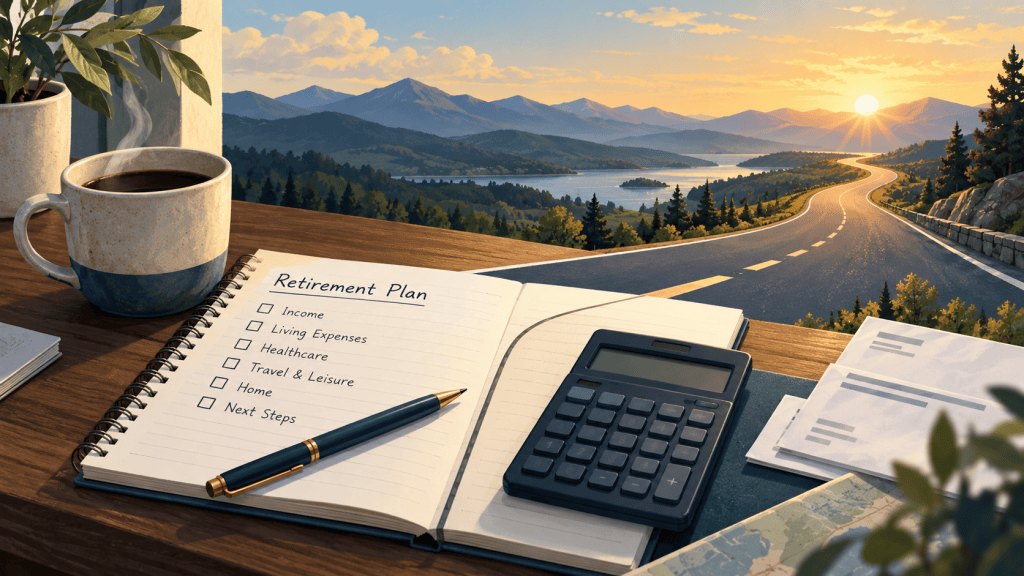
    Retirement planning usually asks one question: Will we have enough money?

    Pretirement asks a more practical question: Can we live comfortably on the income we expect to have after we stop working?

    Instead of waiting until retirement to discover the answer, we can test that future income while we are still earning a paycheck. The experiment reveals whether our retirement plan works in everyday life—and gives us time to improve it if it does not.

    What Is Pretirement?

    Pretirement is a trial run for retirement. We estimate the income we expect to receive after leaving work, limit our current spending to that amount, and observe what happens.

    The basic estimate can include:

    • Projected Social Security benefits
    • Pension or retirement payments
    • A planned withdrawal from retirement savings
    • Other dependable sources of retirement income

    For a simple first estimate, we might combine projected annual Social Security benefits with 5 percent of our expected retirement-account balance. That figure is not a universal withdrawal recommendation. It is a starting point for testing whether our projected resources and expected lifestyle are reasonably aligned.

    We should also account for taxes, health insurance, Medicare premiums, and other costs that may change after retirement.

    Run the Experiment

    Once we estimate our future monthly income, we try living on it while we are still employed.

    Suppose a household currently brings home $8,000 each month but expects about $5,500 per month in retirement. During the Pretirement experiment, the household limits ordinary spending to $5,500 and directs the remaining $2,500 toward improving its financial position.

    The test should be realistic. We still need to budget for irregular expenses such as home repairs, vehicle replacement, travel, medical care, and insurance. Ignoring those costs would make the experiment easier, but less useful.

    Use the Difference to Strengthen the Plan

    If we can live comfortably on the projected retirement income, the money we are no longer spending should not disappear into new purchases. It can be used strategically.

    First, we can pay down debt. Eliminating credit-card balances, vehicle loans, or a mortgage reduces the amount of income we will need in retirement.

    Once high-priority debts are gone, the excess can be directed into retirement savings. That creates a useful feedback loop:

    • Living on less demonstrates that the retirement budget may be workable.
    • Paying off debt reduces future expenses.
    • Additional saving increases future retirement income.
    • The stronger financial position makes the next Pretirement test easier.

    The experiment does more than measure retirement readiness. If we follow through, it can actively improve it.

    Learn From What Does Not Work

    A failed Pretirement test is not a failure. It is valuable information discovered while we still have options.

    If the projected income feels too restrictive, we can examine why. Perhaps our housing costs are too high, debt payments consume too much income, or our estimate omitted an important expense. We may decide to save more, work longer, change our retirement expectations, or look for a different way to structure the transition.

    Discovering the problem several years before retirement is far better than discovering it several months afterward.

    Test More Than the Budget

    Pretirement can also reveal nonfinancial issues.

    When we reduce spending, which activities do we miss? Which expenses contribute meaningfully to our lives, and which were simply habits supported by a larger paycheck? Does our imagined retirement include enough money for travel, hobbies, family, and home maintenance?

    We can also use the experiment to practice the routines retirement will require: managing healthcare, organizing our time, maintaining social connections, and deciding what will give our days purpose.

    Repeat the Test

    Pretirement is most useful when repeated.

    We might run the experiment at age 50, again at 55, and annually as retirement approaches. Each test can use updated Social Security estimates, account balances, pensions, expenses, and retirement dates.

    Over time, the estimates become more accurate and our financial habits become better adapted to the life ahead.

    Retirement should not be the first day we attempt to live like retirees. Pretirement gives us the chance to practice, learn, and adjust while time and employment income are still on our side.