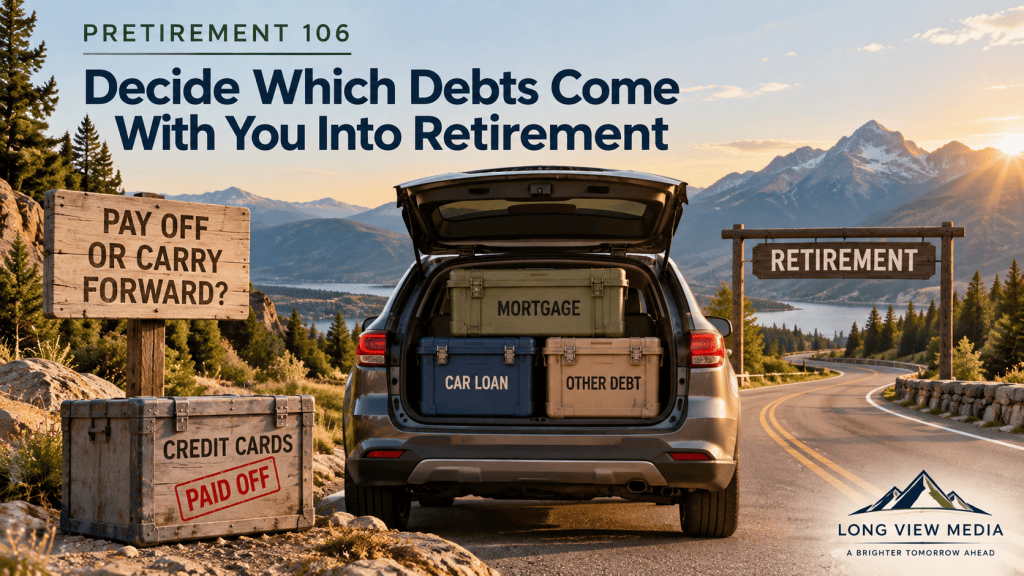
Should you be debt-free before you retire?
It sounds like a question with an obvious answer.
Debt costs money. Retirement usually means giving up a paycheck. Therefore, eliminating every debt before retirement must be the safest choice.
Sometimes it is.
But retirement planning is rarely improved by turning a useful principle into an absolute rule.
A low-rate mortgage is different from a high-interest credit-card balance. A manageable car payment is different from borrowing every month because spending exceeds income. Paying off debt may reduce retirement expenses, but using most of your available cash to eliminate a low-cost loan can create a different kind of vulnerability.
The better question isn’t:
Must we be debt-free before we retire?
It’s:
Which debts do we deliberately want to carry into retirement, and what will they require from our retirement income?
Every Payment Becomes a Retirement Expense
Debt matters in retirement because a payment doesn’t disappear when the paycheck does.
Suppose you’re planning to retire with a $1,500 monthly mortgage payment.
Your retirement resources must provide $18,000 a year just to make that payment.
A $600 vehicle payment requires another $7,200.
Add $400 a month for other debt and you’ve committed another $4,800.
Together, those three obligations require $30,000 of annual cash flow.
That doesn’t automatically mean the debts should be eliminated.
But it does mean they belong in the retirement-income calculation.
When you retire, you aren’t just carrying a balance.
You’re carrying the payment.
Interest Rate Matters, but It Isn’t the Only Thing That Matters
Financial decisions about debt often begin with interest rates.
That’s reasonable.
A debt charging a high interest rate is expensive. Eliminating it can provide a predictable financial benefit because the interest expense disappears.
A very low-rate fixed mortgage presents a different decision. Paying it off may reduce monthly expenses, but doing so could require withdrawing a large amount of money from savings that might otherwise remain available for emergencies, investments, or other retirement needs.
Taxes can complicate the decision further if money must be withdrawn from a tax-deferred retirement account to pay off the debt.
So don’t reduce the question to:
Debt is bad. Pay it off.
Instead ask what eliminating the debt accomplishes and what resources you’ll give up to accomplish it.
High-Interest Consumer Debt Deserves Special Attention
Some debt is particularly difficult to carry into retirement.
Credit-card debt is an obvious example.
Interest rates can be high. Payments may continue indefinitely if balances aren’t reduced. And revolving credit can become a way of financing a lifestyle that retirement income can’t actually support.
If your PreTire budget works only because credit-card balances continue increasing, the budget doesn’t work.
The same concern can apply to other high-cost consumer borrowing.
Before retirement, identify whether debt is financing a temporary circumstance or filling a permanent gap between income and spending.
Those are very different problems.
A temporary debt can be eliminated.
A permanent spending deficit requires a change in the plan.
A Mortgage Is More Complicated
For generations, paying off the house before retirement was a common goal.
There are good reasons for that.
Housing is usually one of the largest household expenses. Eliminating a mortgage can substantially reduce the income needed each month.
It can also provide psychological comfort. Some retirees simply sleep better knowing the house is paid for.
That matters.
But a mortgage shouldn’t automatically be treated like credit-card debt.
Suppose you have a relatively low fixed mortgage rate and sufficient retirement income to make the payment comfortably.
Paying off the mortgage could require moving a substantial amount of money from liquid savings into home equity.
Your net worth may be similar afterward, but the money becomes less accessible.
That tradeoff may be worthwhile.
Or it may not.
The right question isn’t whether retirees should have mortgages.
It’s whether your mortgage fits comfortably within your retirement plan.
Remember That the House Still Costs Money
Paying off a mortgage doesn’t make housing free.
Property taxes remain.
Homeowners insurance remains.
Utilities remain.
Maintenance remains.
Eventually roofs, heating systems, appliances, plumbing, and other components need repair or replacement.
This distinction matters when estimating the benefit of paying off a mortgage.
If your mortgage payment is $1,800 but $600 of that represents taxes and insurance that will continue after the loan is gone, eliminating the mortgage doesn’t reduce your housing cost by the full $1,800.
Know which expenses actually disappear.
Vehicle Debt Can Become a Cycle
A car loan presents another interesting retirement problem.
You may plan to enter retirement with the vehicle paid off.
That’s helpful.
But will you never buy another vehicle?
Someone retiring at 65 could easily spend 20 or 30 years in retirement. Several vehicles may come and go during that time.
So eliminating today’s car payment doesn’t necessarily mean transportation will remain debt-free forever.
Consider the longer-term plan.
Will you save money for the next vehicle?
Buy used vehicles?
Finance replacements?
Keep vehicles longer?
Reduce the number of vehicles in the household?
There’s no universally correct approach.
But don’t build a retirement budget that assumes today’s paid-off car will last forever.
Debt Can Reduce Your Flexibility
One of the most valuable resources in retirement is flexibility.
If markets fall, you may postpone a vacation.
If inflation rises, you may eat at restaurants less frequently.
If an unexpected expense occurs, you may delay a home improvement.
Debt payments are different.
The lender still expects the payment.
That makes debt a relatively inflexible part of retirement spending.
Two households may each spend $70,000 a year, but the household with $25,000 of required debt payments has less room to adjust than the household with very little debt and more discretionary spending.
That’s one reason the amount of debt matters less than the effect the payments have on your financial flexibility.
Debt Changes the Meaning of “Enough”
In Pretirement 103, we defined enough in terms of what your retirement resources need to provide.
Debt changes that calculation.
Imagine that your desired retirement lifestyle requires $75,000 a year, including $15,000 of debt payments.
If those debts are eliminated before retirement, the same basic lifestyle might require closer to $60,000.
That can dramatically change how much retirement savings are needed to support the household.
This is one of the central ideas behind PreTire.
Retirement readiness can improve from both directions.
You can accumulate more resources.
And you can reduce the amount those resources need to provide.
Debt reduction can do both.
This Is the PreTire Effect
Suppose you’re making a $700 monthly payment on a debt.
You pay it off while you’re still working.
Your required future spending falls by $700 a month.
But something else happens.
You still have your paycheck.
The $700 that previously went to the lender is now available.
If you redirect it toward retirement savings rather than allowing it to disappear into additional spending, you’re improving both sides of the retirement equation.
Your future lifestyle requires less income.
Your future resources become larger.
That’s the PreTire Effect.
Debt elimination isn’t merely about becoming debt-free.
It’s about what happens next.
Don’t Let a Paid-Off Debt Become New Spending
This is where a good plan can quietly unravel.
You make the final car payment.
Suddenly $600 a month is available.
A few months later, you can’t quite explain where the $600 went.
Spending expanded.
The payment disappeared, but your lifestyle absorbed the difference.
PreTire provides another approach.
Before making the final payment, decide where that money goes next.
If $600 was going to the car loan, arrange for $600 to begin going toward another deliberate goal.
Perhaps it’s another debt.
Perhaps it’s retirement savings.
Perhaps it’s a cash reserve.
The important thing is to make the decision before the money becomes available.
Otherwise, yesterday’s debt payment can easily become tomorrow’s lifestyle inflation.
Don’t Empty Your Reserves Just to Say You’re Debt-Free
There can also be too much enthusiasm for eliminating debt.
Suppose you have $80,000 in accessible savings and a $70,000 mortgage balance.
Paying off the mortgage might feel wonderful.
But if doing so leaves you with only $10,000 of accessible reserves just before retirement, you’ve exchanged one kind of financial security for another.
Then the roof needs replacing.
Or the car fails.
Or an unexpected medical expense occurs.
You may find yourself borrowing again because the cash that could have handled the problem is now tied up in the house.
Debt reduction should strengthen the retirement plan.
It shouldn’t make the plan brittle.
Be Careful About Using Retirement Accounts to Pay Off Debt
The account balance and the amount available to spend aren’t always the same thing.
Money withdrawn from certain tax-deferred retirement accounts may create taxable income.
A large withdrawal intended to eliminate a mortgage or other debt can therefore have consequences beyond the amount sent to the lender.
It may increase the tax bill.
Depending on circumstances, taxable income can also affect other costs.
That doesn’t mean retirement accounts should never be used to eliminate debt.
It means the decision should be evaluated as a whole rather than looking only at the loan balance.
A $100,000 debt doesn’t necessarily require only a $100,000 financial decision.
Ask Whether You Would Choose the Debt Again
Here’s a useful thought experiment.
Imagine that the debt didn’t exist today.
Would you borrow the money again under the same terms?
If your mortgage were paid off, would you take out a new mortgage for the remaining balance and put the proceeds into your retirement portfolio?
If your car were paid off, would you borrow against it so you could keep the money invested?
Sometimes the answer might genuinely be yes.
Other times the exercise reveals that you’re keeping a debt mostly because it’s already there.
This isn’t a mathematical formula.
It’s a way of making the decision deliberate.
Put Every Debt on the Retirement Timeline
As retirement approaches, list each debt.
For each one, ask:
When will it be paid off if we do nothing differently?
Will that happen before or after retirement?
What will the monthly payment be?
What interest rate are we paying?
Is the rate fixed or variable?
What would it cost to eliminate the debt before retirement?
Where would that money come from?
What happens to our cash reserves if we pay it off?
What happens to our retirement spending if we don’t?
Then decide.
Some debts may become obvious priorities.
Others may reasonably remain.
The goal isn’t to produce a household with a zero in every debt column.
The goal is to understand every obligation you’re carrying across the retirement line.
Test Retirement With the Payments Included
PreTire gives you a simple way to find out whether your decision works.
If you intend to retire with a mortgage, include the mortgage in your PreTire spending test.
If you expect to have a car payment, include it.
If other debt will remain, include those payments too.
Then try living on the retirement income you expect to have.
If the plan works comfortably with those obligations, you’ve learned something useful.
If the payments make the budget uncomfortably tight, you’ve learned something even more useful.
You still have a paycheck and time to respond.
The Goal Is Control
Being debt-free can be an excellent retirement goal.
But zero debt isn’t the objective of Pretirement.
Control is.
You want to know what your retirement income must support.
You want required expenses to leave enough room for the life you intend to live.
You want flexibility when circumstances change.
And you want debt decisions to be deliberate rather than simply inherited from your working years.
So don’t ask whether all debt is good or all debt is bad.
Look at each obligation.
Understand what it costs.
Understand what eliminating it would require.
Understand what keeping it means for retirement income.
Then decide which debts, if any, deserve to cross the retirement line with you.
Retirement doesn’t require being debt-free. But it does require knowing exactly what your debts will demand from the retirement you’re trying to build.
Long View Media provides general educational information, not individualized financial, investment, tax, legal, lending, or retirement advice. Interest rates, tax consequences, retirement needs, loan terms, and individual circumstances vary. Consider the complete financial effect and appropriate professional guidance before making significant decisions about debt, investments, or retirement-account withdrawals.


Leave a Reply